 Facebook
 X
 Pinterest
 Copy Link
Short answer: When mortgage rates are high, asking the seller for concessions and using them for a rate buydown and closing costs usually saves you more than the same amount off the price.
Rates are up and buyers are nervous. The average 30-year fixed hit 7.40% the week of October 15, 2026, per Freddie Mac. A year ago it was 6.34%.
So most buyers do the obvious thing. They try to knock the price down.
A lot of my buyers are leaving New York rent for their first place in Jersey City. It’s not a cheap market. In September 2026, the median sold price here was $720,000 and the median list price was $700,000. At that price, every dollar of your monthly payment counts.
Here’s what I tell my buyers moving from New York to Jersey City instead. Ask the seller for concessions. Use that money to buy down your rate and cover closing costs. In a lot of deals, that puts more money in your pocket than the same dollar amount off the price.
What are seller concessions?
A seller concession is money the seller credits you at closing. You don’t get it as cash. It goes toward costs you’d normally pay yourself.
You can use it two main ways:
- Closing costs. Lender fees, title, prepaid taxes and insurance.
- A rate buydown. You pay “points” up front to the lender, and they give you a lower rate for the life of the loan. One point is 1% of the loan amount.
The seller still gets the same sale price on paper. The money just moves to a different line on the closing statement.
Seller concessions vs. price reduction: the math
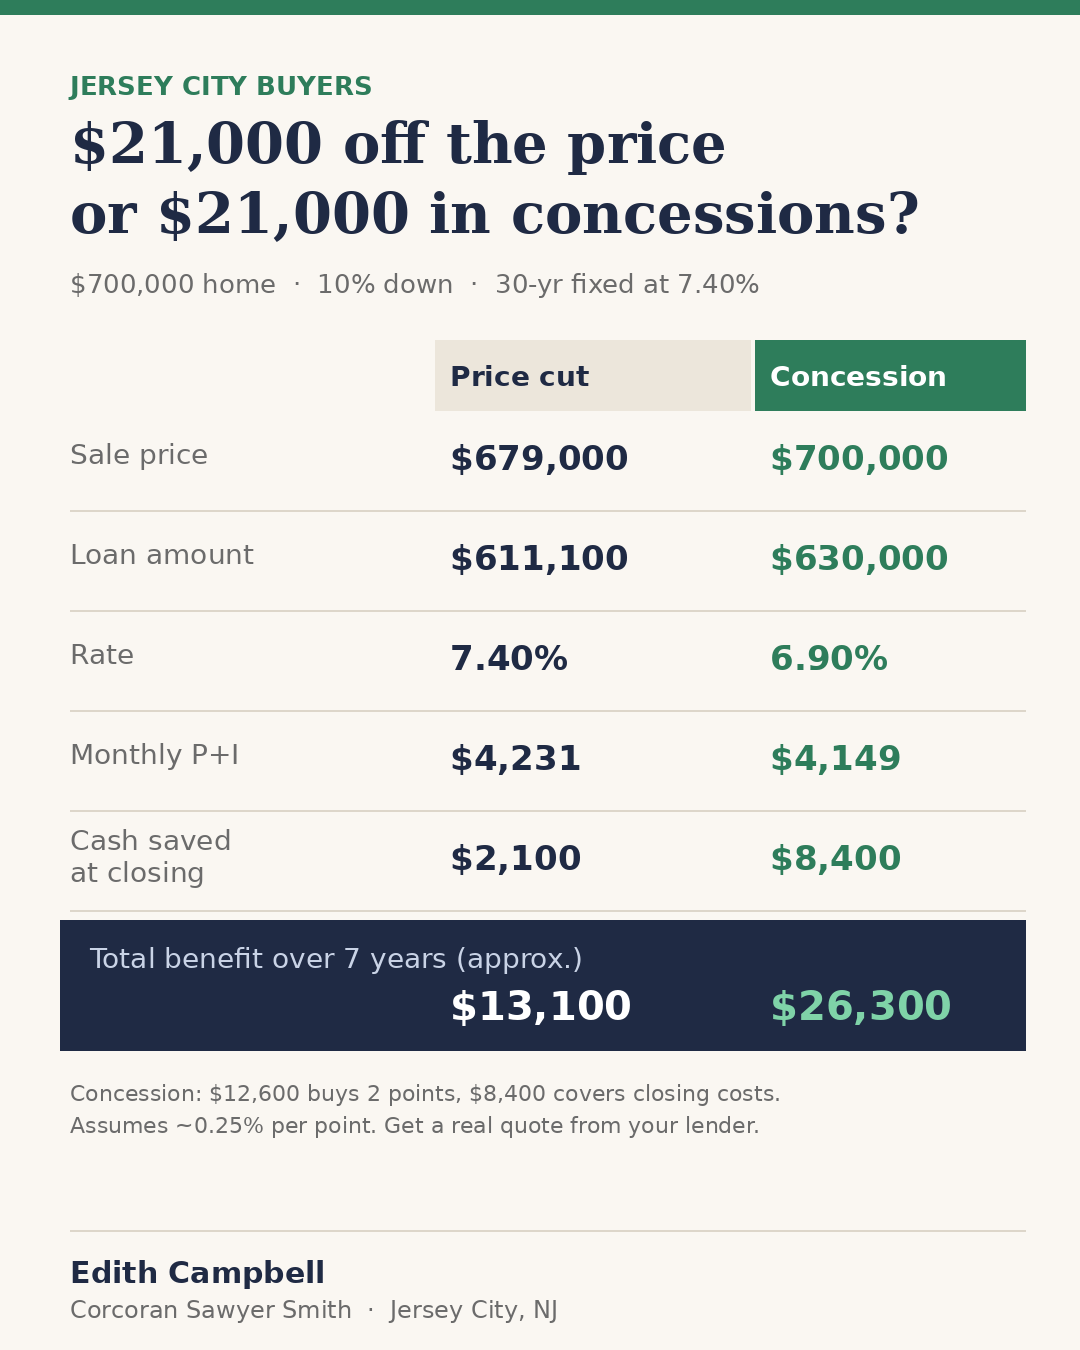
Take a $700,000 Jersey City home. You put 10% down on a 30-year fixed at 7.40%. Your payment would be $4,362 a month before taxes and insurance. You’ve got $21,000 of negotiating room, about 3%.
|
Price cut |
Concession |
|
| Sale price | $679,000 | $700,000 |
| Loan amount | $611,100 | $630,000 |
| How the $21,000 is used | Lowers the price | $12,600 buys 2 points, $8,400 covers closing costs |
| Rate | 7.40% | 6.90% (assumes ~0.25% per point) |
| Monthly principal + interest | $4,231 | $4,149 |
| Cash saved at closing | $2,100 (smaller down payment) | $8,400 (closing costs covered) |
| Total benefit over 7 years | about $13,100 | about $26,300 |
The concession wins on both fronts. A lower payment every month, and more cash left in your account on closing day.
That second part matters more than people think. Running out of cash at closing kills more deals than the payment does.
One note. How much rate a point buys changes by lender and by week. Get a real quote from your lender before you write the offer.
Why do sellers agree to concessions?
To the seller, $12,000 off the price and $12,000 in credits cost about the same. They walk away with roughly the same net.
And right now, sellers need you more than you need them. Jersey City has 7.68 months of inventory, up about 51% from a year ago. That’s a buyer’s market. Homes are still selling close to asking, at 99.7% of list, but there’s more on the shelf and you have room to ask.
But a concession keeps the sale price higher. That protects their number on paper. It also helps the comps for their neighbors and the building.
Sellers sitting on a listing in this market want a deal that closes. A buyer who can actually afford the payment is a buyer who makes it to the closing table.
How much can a seller pay toward closing costs?
Concessions have caps, and they depend on your loan.
| Loan type | Typical seller concession cap |
|---|---|
| FHA | 6% of the price |
| Conventional, primary home or second home | 3%, 6% or 9%, based on your down payment |
| Conventional, investment property | 2% |
Your lender has the final word.
A few other things to know:
- The home still has to appraise. If the price is propped up by credits and the appraisal comes in low, you’ll be back at the table.
- Concessions can’t cover your down payment. Fannie Mae doesn’t allow it.
- Points pay off over time. If you plan to sell or refinance in a year or two, a buydown may not be worth it. Ask your lender for the break-even month.
- Unused credit can be lost. If the credit is more than your actual costs, you usually don’t get the extra back.
How to ask for seller concessions in your offer
- Talk to your lender before you make an offer. Ask what one point buys you this week.
- Decide your split. How much goes to the rate, how much to closing costs.
- Write it into the offer as a seller credit. Don’t leave it for later.
- Keep the total inside your loan’s cap.
Rates will move. Your payment is locked for 30 years once you close. Negotiate for the thing that sticks.
If you’re looking in Hudson County and want to run these numbers on a real listing, reach out. I’ll walk you through it.
FAQ
Is it better to ask for seller concessions or a lower price? When rates are high, concessions usually win. A rate buydown lowers your payment every month, and covered closing costs keep more cash in your account on closing day.
What is a mortgage rate buydown? You pay points to your lender up front for a lower interest rate. One point costs 1% of the loan amount. A seller concession can pay for those points.
How much does one mortgage point lower my rate? Often around 0.25%, but it changes by lender and by week. Get a quote before you write your offer.
How much can a seller contribute to closing costs in NJ? It depends on the loan, not the state. FHA allows up to 6%. Conventional loans allow 3%, 6% or 9% depending on your down payment, and 2% for investment properties.
Can seller concessions pay my down payment? No. Concessions can cover closing costs and points, but not your down payment.
Do seller concessions affect the appraisal? The home still has to appraise at the contract price. If it comes in low, you’ll have to renegotiate.
Edith Campbell is a licensed real estate salesperson with Corcoran Sawyer Smith, helping buyers and sellers in Hudson County, NJ, including Jersey City, Bayonne, and Hoboken. She’s also a notary with six years at the closing table. Reach out if you are looking to buy.
Market data: Corcoran Sawyer Smith Market Trends report for Jersey City, powered by RPR, September 2026. Rates: Freddie Mac, week of October 15, 2026.